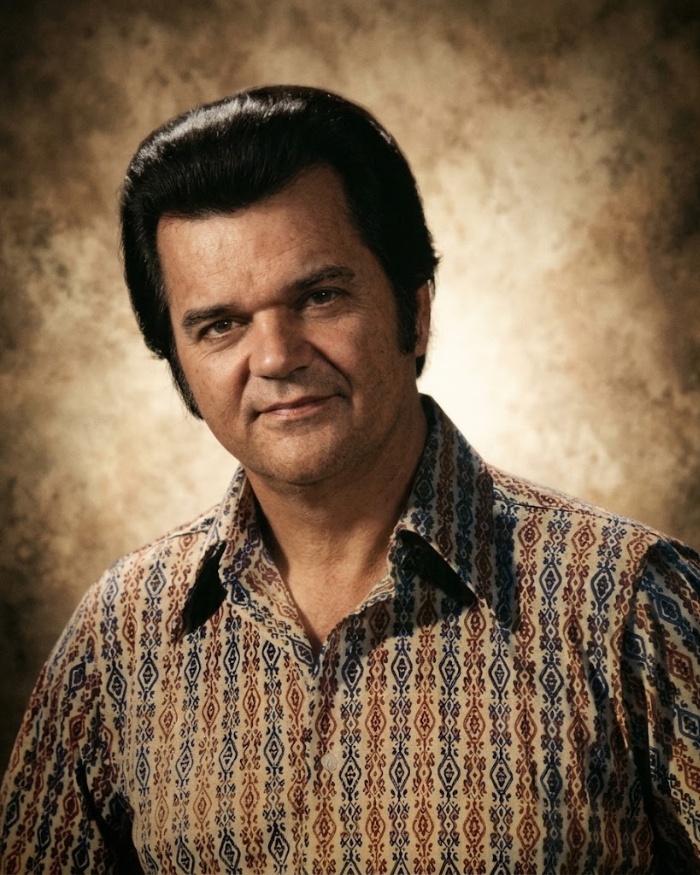
On his 1973 and 1974 federal income tax returns, country singer Conway Twitty—filing under his legal name, Harold L. Jenkins—deducted $92,892.46 and $3,600 in personal checks he had written to roughly 75 friends, bandmates, and fans. Every dollar went to cover losses from a defunct fast-food company he had no legal duty to rescue.
The venture had started in late 1968, just as Twitty was building a streak of country chart-toppers out of Oklahoma City. Seeking a business that would carry his name alongside the booming celebrity restaurant chains of the era, he incorporated Twitty Burger, Inc., complete with a yellow “Twitty Bird” mascot and a signature “Twitty-Bird” burger topped with pineapple.
Instead of turning to Wall Street banks, Twitty raised capital from approximately 75 people inside his own circle. The roster of backers included fellow country artists Merle Haggard and Sonny James, Nashville songwriter Harlan Howard, members of Twitty’s touring band, his manager, local acquaintances, and working-class fans who invested personal savings because his name was on the sign.
When the first restaurant opened in 1969, fans crowded the counter, and the company quickly acquired additional properties across Oklahoma and Texas. Behind the scenes, rapid overexpansion, lease obligations, supply-chain mismanagement, and an early-1970s economic downturn drained the company’s cash reserves.
By late 1970, the Securities and Exchange Commission investigated how the company’s debentures had been registered, blocking further stock sales just as operating debts mounted. By 1971, nearly every Twitty Burger location had shut its doors, leaving the corporation without cash or physical assets to pay back the people who had bought in.
Under corporate law, Twitty Burger, Inc. was a separate legal entity, allowing its founder to walk away from the defunct company’s obligations without personal liability. Twitty refused to take that protection and promised his backers that he would make them whole out of his future music earnings.
Because he did not have the cash on hand in 1971 to settle the accounts at once, he spent the next two years packing his touring calendar across dozens of states. Between concert dates and Decca studio sessions that produced hits such as “Hello Darlin'” and “You’ve Never Been This Far Before,” he funneled his performance fees and recording royalties into a repayment fund.
Throughout 1973 and 1974, he mailed checks directly to the investors until every person had recovered their principal, with interest added on several long-held debentures. When his accountants deducted the $96,492.46 total as an ordinary and necessary business expense under Internal Revenue Code Section 162, the Internal Revenue Service disallowed the claim, citing the general rule that a taxpayer cannot deduct voluntary payments made to cover another corporation’s debts.
The dispute reached the United States Tax Court in *Harold L. Jenkins v. Commissioner*, decided on November 3, 1983, as T.C. Memo. 1983-667. On the witness stand, Twitty explained that in country music a handshake carried more weight than a legal shield, and that he could not step onto a stage to sing about honesty, heartbreak, and loyalty while friends, fellow artists, and fans sat in the crowd having lost their savings to his company.
Country music historians and industry experts corroborated his testimony, explaining to the court that a country performer’s career and box-office survival depended directly on personal integrity in the eyes of working people. Applying the two-part test from *Lohrke v. Commissioner*, the court examined both Twitty’s motive and whether the payments bore a direct connection to his trade as an entertainer.
The Tax Court ruled in Twitty’s favor, concluding that while he felt a moral duty to his backers, his primary business purpose was protecting the personal reputation essential to his livelihood as a country singer. Had prominent investors such as Merle Haggard or Sonny James sued him, or had word spread among fans that he left ordinary backers empty-handed, his earning power in country music would have suffered.
In a footnote at the end of T.C. Memo. 1983-667, the court closed the ruling with a rhyming “Ode to Conway Twitty” summarizing why the deductions stood, and the IRS chose not to appeal through a matching verse of its own. More than four decades after the ruling, first-year American law students studying federal income tax still open their textbooks to *Harold L. Jenkins v. Commissioner* and read the accounting of the $96,492.46 the country singer paid out of his own pocket when the last Twitty Burger signs came down.